Once I began thinking of Goliath as an architecture rather than a company, another question became unavoidable.
Where should the startup sit inside the new architecture?
It is not enough to know that the old system can be improved. The founder has to decide what kind of company can carry that improvement into the market and retain enough control to capture the value created.
I have come to see two strong challenger positions and one honest incumbent position.
The company can become the challenger capable of delivering the complete outcome.
Or it can own an indispensable layer that makes a challenger possible.
It can be David, or it can stand beside David and supply the indispensable sling.
It can also strengthen the incumbent architecture. Many excellent businesses do. The mistake is not choosing that position; the mistake is describing a replaceable supplier as though it controls the revolution.
Between those positions lies a common and dangerous outcome: a technically impressive company that performs difficult work but remains replaceable inside somebody else's system.
The strategic task is to avoid that orphan position.
Position one become David
To become David is to take responsibility for the buyer's outcome.
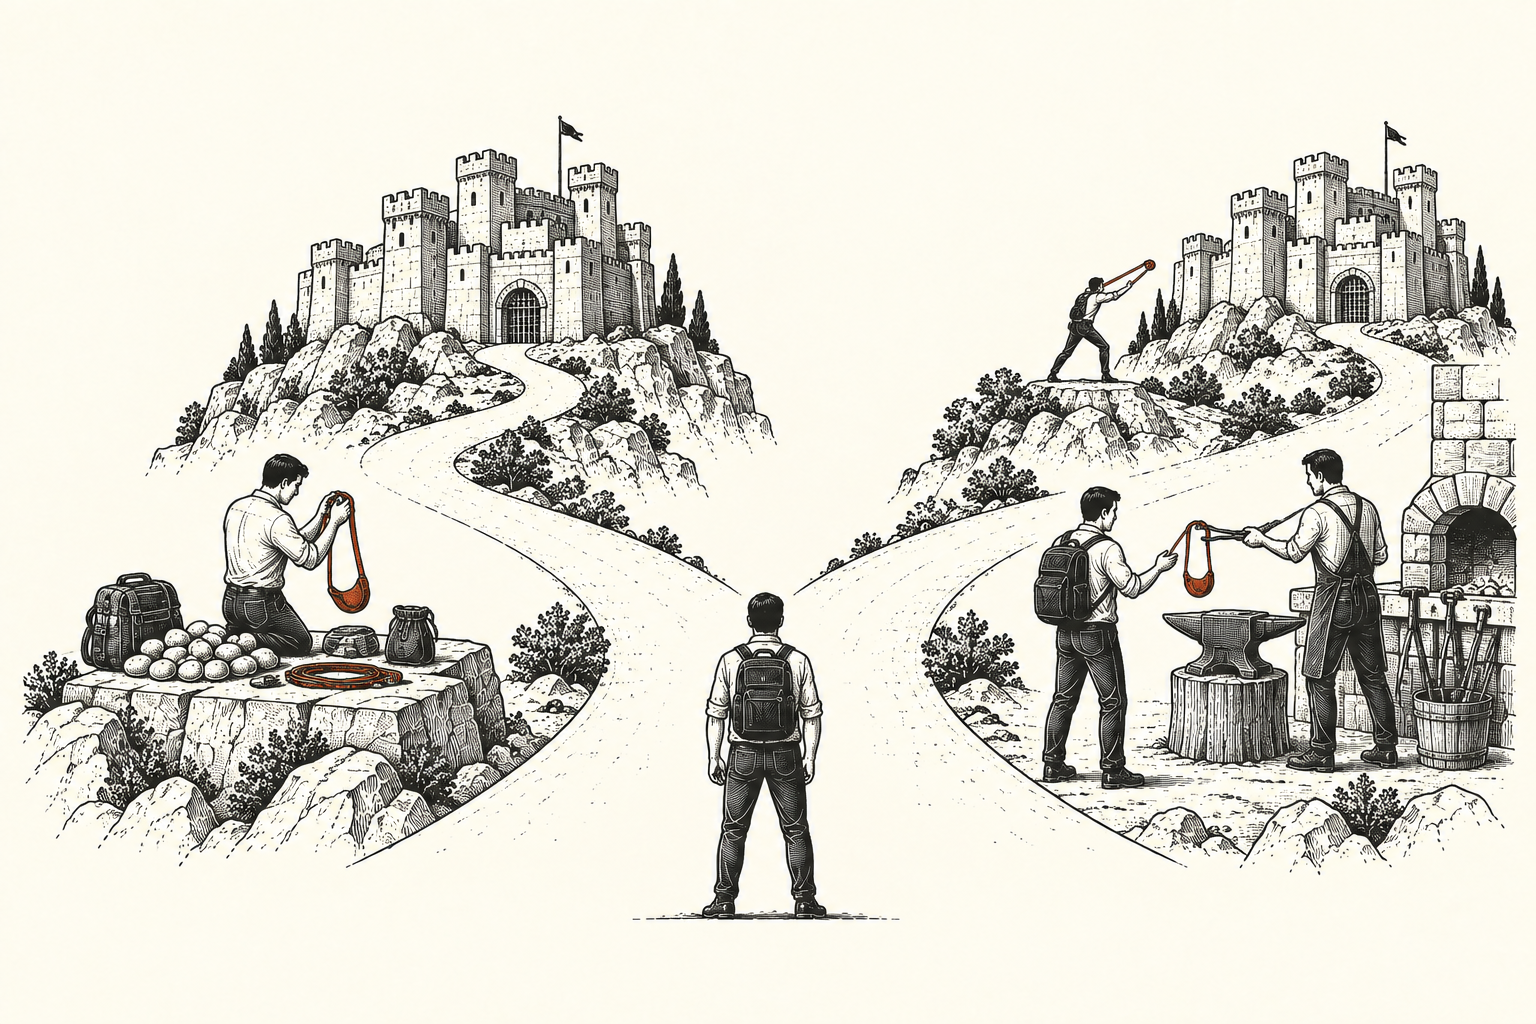
The company does not merely provide a technology and hope the surrounding system makes it useful. It assembles or controls enough of the product, integration, qualification, manufacturing, service and customer relationship to make the promise true.
I call this the complete operating vehicle.
The phrase “complete” can be misleading. It does not mean the startup owns every factory, writes every line of software, employs every service technician or vertically integrates the entire supply chain. It means the company controls the complementary assets that determine whether the outcome is delivered and whether the company gets paid.
Control can come through:
• Ownership.
• Contract.
• Interface design.
• Qualification history.
• Exclusive access.
• A privileged customer relationship.
• A standard others must follow.
• A partner whose incentives are tightly aligned.
The question is not how much the company owns in absolute terms. It is whether the company can make and keep the promise it sells.
The minimum complete vehicle
Founders often face two opposing temptations.
The first is to stop too early: build the technically differentiated component and assume somebody else will productise, qualify, distribute and service it without taking most of the economics.
The second is to integrate too far: build every surrounding capability because each appears important, exhausting the company before the core advantage reaches a buyer.
The useful boundary lies between them. I would ask:
What is the minimum system the company must control for the buyer to experience the promised outcome?
That system differs by market.
A semiconductor design may need software, packaging, reference implementations and integration support before it becomes a product a customer can adopt. A biological input may need formulation, application data, quality systems and distribution into the customer's workflow. An industrial machine may need installation, monitoring, service and performance guarantees. A defence subsystem may need integration, environmental testing, documentation and a procurement path.
The complete operating vehicle includes whatever the buyer cannot be expected to assemble alone.
This is one reason apparently narrow technologies often become broader companies. The market does not reward them for remaining pure. The buyer forces them to absorb enough complexity to deliver the result.
Position two arm David
Not every company should become the complete challenger.
Some technologies are more powerful as enabling layers used across several systems. Their opportunity is not to own the final customer outcome, but to become difficult to remove from every credible path to that outcome.
The enabler is attractive when the layer is:
• A genuine bottleneck.
• Difficult to substitute.
• Responsible for a decisive portion of performance or economics.
• Portable across more than one customer or system.
• Protected by research, process knowledge, data, manufacturing learning, qualification or integration.
• Valuable enough for the supplier to retain pricing or bargaining power.
The strongest enabling layer does not merely participate in a growing market. It improves as the surrounding market grows.
More deployments may produce more process data, qualification history, design knowledge or ecosystem support. The layer becomes easier to adopt and harder to replace. Distribution by system-level partners can increase the enabler's reach without requiring it to build the entire market itself.
This is how a company can arm many Davids.
Position three strengthen Goliath honestly
Some companies should sell into the incumbent architecture rather than overthrow it.
A new material may improve an established manufacturer's product. A specialised model may become a feature inside an incumbent workflow. A component supplier may achieve attractive economics because the existing system already owns qualification, distribution, service and the final customer relationship.
There is nothing inferior about this position. It can reach market faster, require less capital and place the technology inside a system buyers already trust.
But the company should describe the economics accurately.
If the incumbent owns the interface, qualification, field data and ability to switch suppliers, the startup may be a valuable vendor rather than a new platform. Its moat must then come from something the incumbent cannot easily internalise or source elsewhere: process knowledge, a steep learning curve, protected manufacturing, unique data, regulatory history or a performance advantage that continues moving.
The strategic danger is narrative inflation. A company says it is transforming an industry while its customer is transforming the company into an input.
The right question is not whether the startup appears central in the pitch. It is whether the surrounding architecture becomes more dependent on the startup after deployment.
The layer must remain indispensable
“We are a platform” is not a substitute for power.
A component can be technically difficult and economically weak. If the system integrator can dual-source it, redesign around it, demand full customisation or capture all of the customer relationship, the component supplier may create more value than it retains.
I would test an enabling layer through four questions.
Bottleneck importance
Does this layer determine whether the overall system can reach the required outcome?
Substitutability
What would it cost—in money, time, qualification or lost performance—to replace the company?
Portability
Can the same underlying capability travel across customers, programmes or markets without being rebuilt each time?
Value capture
After the integrator, manufacturer, distributor and service provider are paid, does the company retain attractive economics and strategic control?
An enabling technology becomes a company when these conditions reinforce one another. Difficulty alone is insufficient.
The orphan technology trap
The dangerous position is a technology too incomplete to reach the buyer independently and too replaceable to retain power inside somebody else's product.
I call it an orphan technology because responsibility for its future is unclear.
The startup expects an integrator to carry it into the market. The integrator expects the startup to complete more of the qualification and product work. The customer likes the technology but does not know who will guarantee performance. Investors see technical differentiation but cannot see the route to repeat demand.
The company may survive through pilots, custom engineering and strategic projects. Those activities can be useful, but they can also conceal the absence of a reusable company architecture.
Typical symptoms include:
• Every customer requires a substantially different product.
• Revenue depends on founder-led integration.
• Qualification work does not transfer to the next buyer.
• The partner controls all field data and customer feedback.
• The startup cannot explain what remains proprietary after outsourced engineering is removed.
• The technology is praised but rarely specified into a repeat purchase.
• A larger partner can replace the company without changing the buyer's outcome.
The trap is not that the startup sells a component. The trap is that the component never becomes a control point and the startup never becomes a complete vehicle.
From component to control point
An enabling company can strengthen its position without attempting to own the whole system.
It can accumulate control through:
Interfaces
If other products are designed around the company's interface, switching becomes more difficult and the layer becomes a reference point for the system.
Process knowledge
Manufacturing and operating knowledge can remain difficult to transfer even when the underlying science is understood.
Proprietary data
Field use can improve models, calibration, process recipes or performance predictions in ways competitors cannot reproduce from public information.
Qualification history
Repeated acceptance can make the company the lower-risk choice even when alternatives appear technically comparable.
Workflow integration
A component that becomes embedded in the customer's operating process can control more value than one sold as an isolated object.
Ecosystem support
Tools, documentation, developer support, service partners and compatible products can make adoption easier while increasing the cost of leaving.
These are not tricks for locking in a customer. They are ways of making the layer more useful and dependable as part of a larger system.
From arming David to becoming David
The two positions are not permanent identities.
A company may begin with an enabling component because that is the fastest route to qualification and customer learning. Over time, it can accumulate enough integration knowledge, distribution and buyer trust to deliver a larger system.
The sequence might be:
→ qualified product
→ product family
→ integrated system
→ complete customer outcome
At some point the company stops merely arming David and becomes a challenger itself.
The reverse can also happen. A full-system company may develop an internal technology so powerful and portable that it becomes valuable as an enabling platform for other challengers.
The strategic position can change as the company's capabilities change.
This matters because founders sometimes make the wrong decision too early. They declare themselves a platform before proving one product, or attempt a full-stack system before earning the technical and customer knowledge required to integrate it. The direction may be correct while the timing is wrong.
The better question is:
What position can the company defend now, and what evidence would justify expanding it later?
Control without ownership
This is where the language of vertical integration can become unhelpful.
The company does not need to own a complementary asset merely because the asset is important. It needs reliable control over the asset's contribution to the customer promise.
I would divide activities into four categories:
Own
The activity contains the company's core differentiation, learning or bargaining power.
Control
The activity may be performed by a partner, but the company specifies the interface, quality, evidence and incentives required.
Partner
The activity is strategically important but can be shared with an aligned organisation that brings scarce capability or access.
Purchase
The activity is necessary but sufficiently standard that market procurement is reliable.
The error is not outsourcing. The error is outsourcing the learning, evidence or customer relationship on which future power depends.
The company-design test
The investment unit I use in the broader report is:
This chapter deals with the first term.
What remains inside the company after commodity engineering, contractors, partners and outsourced manufacturing are removed?
The answer may be a complete mission product. It may be architecture, process knowledge, proprietary data, integration, qualification history, an interface or a manufacturing capability.
But it must be more precise than “our intellectual property.”
The founder should be able to explain:
• What the company uniquely controls.
• Why the buyer or integrator depends on it.
• How the position strengthens after deployment.
• How the company captures a meaningful share of the value.
• What would have to happen for the position to become weaker.
If those answers are unclear, the technology may be advanced while the company remains strategically incomplete.
Questions I now ask
1. Does the company sell a component, a product, a system or an outcome?
2. What is the minimum complete vehicle required for the buyer to receive that outcome?
3. Which activities contain proprietary learning or bargaining power?
4. Which activities must be controlled but need not be owned?
5. If the company remains an enabler, what makes its layer indispensable?
6. How expensive is replacement after technical and qualification costs are included?
7. Can the same capability travel across customers without bespoke rebuilding?
8. Who owns the field data and customer feedback?
9. Is the company accumulating a control point or funding somebody else's moat?
10. What evidence would justify moving from component to system—or from system to platform?
The strategic choice is not between ambition and modesty. An enabling layer can be more powerful than a complete product, and a complete product can be weaker than an indispensable component.
The choice is about where control can accumulate.
Become the system that defeats the incumbent architecture—or own the layer that makes its defeat possible.
Then earn the evidence required for the buyer to believe it.